


Cash Advance Now - Bear Loan
4.7117.00 Reviews
App Specs
- Version
- 2.2.3
- Updated On
- License
- Free
- Downloads
- 10,000+
- Developer
- EPUTSTG QUALITY
- Categories
- Finance
- Platform
- Android
Screenshots
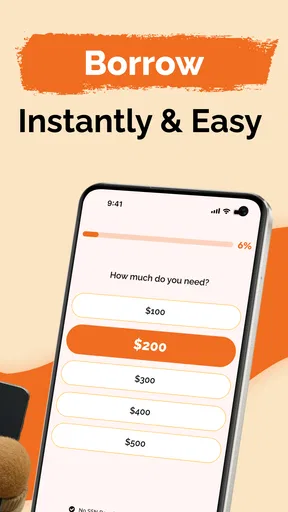
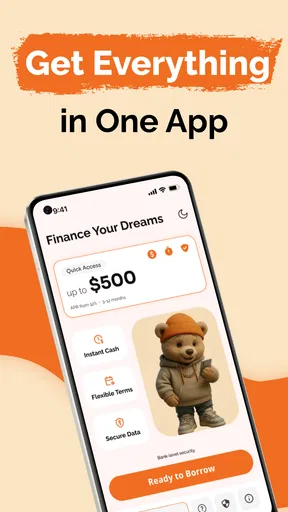
 Analysis by AppCompare
When an unexpected bill lands between paydays, it is tempting to judge a cash-advance app by one question: how quickly might it help? I’d look at a few others first: what repayment would mean for my next paycheck, how clearly I can understand the terms, and whether borrowing is truly better than asking for an extension or using savings. Cash Advance Now - Bear Loan is aimed at people exploring online loan options, but a name and a short pitch are not enough reason to borrow. I’d treat it as a starting point for assessing an offer, not as a promise that cash is guaranteed.
Separate the bill from the borrowing decision
Before opening any finance app, I’d write down what has to be paid, when it is due, and what happens if payment is delayed. That quick check helps distinguish an immediate emergency from a problem that feels urgent only because it is stressful. It also gives me a clear amount to compare against any proposed advance, instead of letting the available borrowing amount set the size of the decision.
I’d also decide what I am willing to do if the app does not lead to a suitable option. For example, I might call the biller, ask about a short extension, or postpone a purchase that is not essential. Having a fallback matters because it reduces the pressure to accept terms simply to feel that I have made progress. For a cash shortfall that repeats, I would look beyond a one-time fix and identify which regular expense or timing mismatch is causing it.
Start with the repayment, not the urgency
I find it useful to turn a stressful cash gap into a small, concrete decision: name the bill, set the maximum repayment your budget can absorb, and check the date that money must leave your account. That keeps the urgency from setting the terms for you. In the next section, I’ll look at how Bear Loan’s focused role compares with other ways to handle a shortfall.
What I would check before applying
My first decision criterion is the full amount I would have to repay and when it would be due. Before proceeding with any cash advance, I’d look for the amount available, any fees or other costs, the repayment date, and what happens if I cannot pay on time. Those details determine whether a short-term advance solves a problem or simply pushes it into the next pay period. I would not make a decision until the terms are clear enough to compare with other options.
The next question is fit. Is the expense urgent, necessary, and specific, or am I trying to cover a budget gap that is likely to recur? A one-off car repair or an essential bill may call for a different response from routine overspending. If the shortfall appears every month, borrowing can make the underlying problem harder to fix. I’d first map out the next few weeks of income and bills, then see whether the repayment leaves enough for essentials.
There is also a practical difference between an app that introduces a borrower to loan options and one that clearly lays out a complete offer. The available description presents Bear Loan as a partner among apps with cash-advance options for online loans; it does not, by itself, establish that every applicant receives an advance or the same terms. I’d therefore avoid assuming that installing the app means approval, a particular amount, or immediate funds.
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
Who is most likely to find it useful
Bear Loan is a finance app from EPUTSTG QUALITY, and its focus makes it most relevant to someone who is actively exploring online cash-advance choices. It may be worth considering if you want to investigate a short-term option through a phone rather than begin with a broader personal-loan search. The app is free to install, which lowers the initial barrier to looking at it, but free access should not be confused with a free loan. Any borrowing costs need to be judged from the actual offer.
Its audience is not necessarily everyone who needs money quickly. If you already have an overdraft, a credit-union option, an employer-based advance, or a payment plan available, I’d compare those first. The best choice depends on the terms you can actually obtain and your ability to repay, not on which option sounds quickest. If you do not have a reliable repayment plan, I would skip borrowing and contact the bill provider or seek local financial guidance instead.
Where Bear Loan fits among cash-advance choices
I’d compare Bear Loan with alternatives by asking what problem each route is meant to solve, rather than assuming one type of app is automatically faster or cheaper. A cash-advance option may be worth exploring for a specific, short-lived need, while a payment arrangement or a conventional loan may suit a different timeline. That distinction helps clarify where this app fits—and where another route may make more sense.
The value of a focused starting point
The strongest case for Bear Loan is its narrow purpose: it is presented around cash advances and online loan options rather than as a general-purpose finance toolkit. That focus can suit someone who has already decided to compare borrowing routes and wants to explore them in an app. Its current version is 2.2.3, and the app is listed for Android 7.0 and up, so people using older compatible Android devices may be able to consider it without needing a recent operating-system version.
Its public reception offers some context, but not a substitute for reviewing terms. The app has a 4.7 average from around 4,300 ratings and has been installed over 10,000 times. That gives a prospective user a sense that other people have engaged with it, yet ratings cannot tell you whether a particular offer is affordable, whether you will qualify, or how the experience will suit your circumstances. I’d read feedback for recurring themes and still make the repayment decision on the written terms in front of me.
The age classification is Everyone, which describes the app’s content rating; it does not mean borrowing is appropriate for every age or financial situation. Anyone considering a loan should be able to understand the agreement and meet its obligations. If you are young, financially dependent on someone else, or unsure what a repayment commitment means, involve a trusted adult or adviser before applying.
A realistic way to use it without rushing
Imagine your phone stops working just before a work shift, and replacing it is necessary to keep earning. I would first check whether the repair is cheaper, ask the provider about a payment arrangement, and see whether a friend or family member could help without creating strain. If I still considered a cash advance, I would use Bear Loan only as one part of the comparison: note the proposed repayment, compare it with the next payday’s essential expenses, and decline if the remaining balance would leave me short on rent, food, or transport.
A useful, less obvious habit is to decide on a maximum repayment before opening any borrowing app. That limit should come from a realistic budget, not from the largest amount offered. I’d also write down the expense the advance is meant to cover. If the proposed amount exceeds that need, or if I start adding nonessential spending because more money appears available, I would stop and reassess. These simple guardrails help prevent urgency from turning into a larger commitment than intended.
Another practical trade-off is the time spent comparing offers versus the pressure to act. A fast-looking route can be attractive when a bill is due, but taking a few minutes to compare the total repayment, due date, and late-payment consequences may prevent a more expensive mistake. I would save or note the terms before deciding, so I could compare them calmly rather than rely on memory after viewing several options.
Questions I would answer before accepting anything
Would I know exactly who is making the offer and who I would repay? I would check the agreement itself, rather than infer those details from an app’s name or introductory wording. I’d also confirm the repayment method and date, and make sure the account I expect to use will have enough funds then. If a screen leaves the lender, amount, or obligation unclear, I would pause instead of treating the next button as a harmless step.
Could I repay early, change a date, or get help if my circumstances change? I would look for the relevant terms before agreeing, because flexibility can matter as much as the initial amount. I’d keep a copy or clear note of the final offer and the payment date, then set a reminder a few days ahead. This small administrative step is especially useful when the due date falls near rent, utilities, or another large regular bill.
When another route may be better
Compared with a bank or credit-union personal loan, a cash-advance route may appeal to someone seeking a smaller, short-term solution, while a conventional loan may be better suited to a larger expense that can be repaid over a longer period. Neither category is automatically cheaper or easier to obtain; the actual terms matter. I would compare the total cost and schedule rather than assume that the label “cash advance” means the simplest or most affordable choice.
For a bill that is already overdue, contacting the service provider directly may be more useful than borrowing. Some providers can discuss payment timing or a plan, and asking does not require taking on a new loan. For a recurring cash shortfall, a budget review or free nonprofit financial counseling may address the cause more effectively. And if the need is discretionary, waiting until the next payday is often the cleanest alternative because it avoids a repayment obligation altogether.
Bear Loan is not the right pick for someone who needs confirmed cash by a specific hour, cannot accept uncertainty about approval, or has no safe way to repay. The app’s short description is not a guarantee of availability or timing. I would also steer away if the borrowing would be used to repay another short-term loan; that pattern can stack obligations and make the next month more difficult.
What switching options really costs
Trying a different app or lender is not always a free reset. Applications can take time, and a separate lender may use different eligibility checks and repayment terms. Before switching, I’d make sure I understand whether I have already agreed to anything, whether an application is still in progress, and whether I am comparing the same amount and repayment period. I would avoid submitting applications in a rush simply to see which one responds first.
There is also a privacy and attention cost to considering multiple financial apps: each can ask for information as part of its process. I would share only what is needed to assess a legitimate offer, read the relevant screens carefully, and stop if a request or term is unclear. This is a general precaution, not a claim about Bear Loan’s specific data practices. The practical point is to make the decision deliberately rather than treating repeated applications as harmless browsing.
If you install it and decide it is not suitable, moving on is straightforward in principle: compare another route or avoid borrowing. The more important switching cost is the possibility of losing time while an urgent bill remains unresolved. For that reason, I’d contact the person or company expecting payment at the same time as I compare options, rather than wait for an app process to solve the whole problem.
My recommendation
I would consider Bear Loan if I were an adult exploring online cash advances, had a one-off essential expense, and could repay a clearly stated amount without compromising my next set of basic bills. It is free to install, focused on a specific borrowing need, and has a 4.7 average from around 4,300 ratings, which makes it reasonable to investigate rather than dismiss outright. Those points do not remove the need to examine the offer closely.
I would skip it if I needed certainty before proceeding, if the expense could wait, or if repayment would depend on borrowing again. In those cases, a payment arrangement, a lower-cost option available to me, or a plan to delay the purchase is a better first move. My advice is simple: judge the repayment before the advance. If the terms are clear and fit a budget you can genuinely meet, the app may be one place to explore; if not, walking away is a sound financial decision.
Pros
- Simple application flow makes it easy to review available loan options.
- A useful option for handling an unexpected short-term cash need.
- Loan details can be checked before deciding whether to proceed.
- Applying through a mobile app may save time compared with visiting a lender.
- Can help users compare the repayment amount with their budget.
Cons
- Approval and loan terms may depend on eligibility and personal circumstances.
- Borrowing costs can be high; review fees and APR carefully before accepting.
- Repayment deadlines may be short
- leaving little time to repay.
- Late or missed payments may lead to additional charges or other consequences.
- Sharing financial and personal information is required to apply.
FAQs for Cash Advance Now - Bear Loan
What is Cash Advance Now - Bear Loan?
Cash Advance Now - Bear Loan appears to be a financial app intended to help users explore or request short-term cash advances or personal loans. The exact services, loan amounts, fees, eligibility rules, and availability can depend on your location and the app’s current terms. Before applying, review the official product disclosures and confirm which company will handle your application, funds, and repayments.
Is Cash Advance Now - Bear Loan a direct lender?
Do not assume that the app itself lends money. Some finance apps act as loan-matching services that pass application details to lenders or other providers, while others offer products directly. Check the app’s privacy policy, terms, and lender disclosures to understand who receives your information, who makes the lending decision, and whom you would contact about a loan or repayment.
What information may I need to apply?
An application may request identifying and contact details, income or employment information, banking details, and permission to verify information or assess eligibility. Requirements vary by provider, and submitting an application does not guarantee approval. Read each permission request and the privacy policy before sharing sensitive data, and only provide information through the official app listing or a verified company website.
What fees, interest, and repayment terms should I check?
Before accepting any offer, look beyond the advertised advance amount and review the annual percentage rate where applicable, finance charges, origination or other fees, repayment dates, late-payment consequences, and total amount due. Short-term borrowing can be expensive, and missed payments may create additional costs. Compare the written disclosure with your budget, and do not proceed if key terms are unclear.
Is Cash Advance Now - Bear Loan available and safe to use everywhere?
Availability and eligibility can vary by country, state, or region, and financial products may be restricted by local rules. Download the app only from a trusted official app store, verify the developer’s identity, and inspect recent reviews and requested permissions. No app can guarantee approval or instant funding for every user, so confirm the provider, security practices, and local availability before applying.


